tweetkeep

BREAKING: Banking Crisis - Guarantee Deposits or Banking Collapse
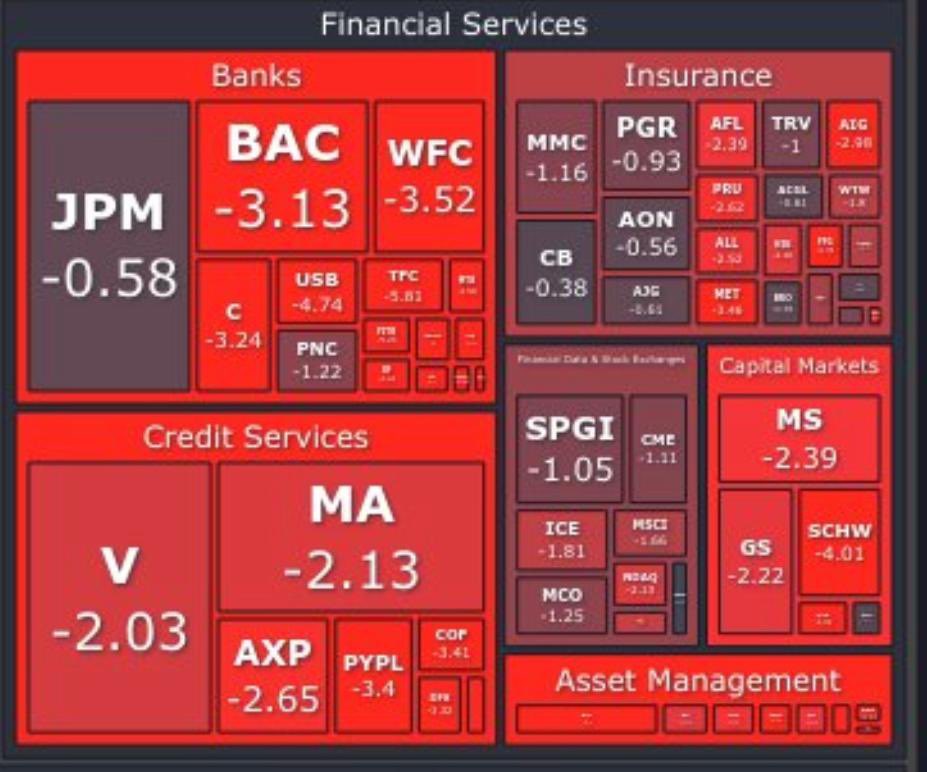
Senior banking executives have stated that ALL deposits must be guaranteed above the $250,000 limit in order to prevent a regional banking crisis.
The last time this was increased was in 2008 after the Global Financial Crisis where the limit was $100,000.
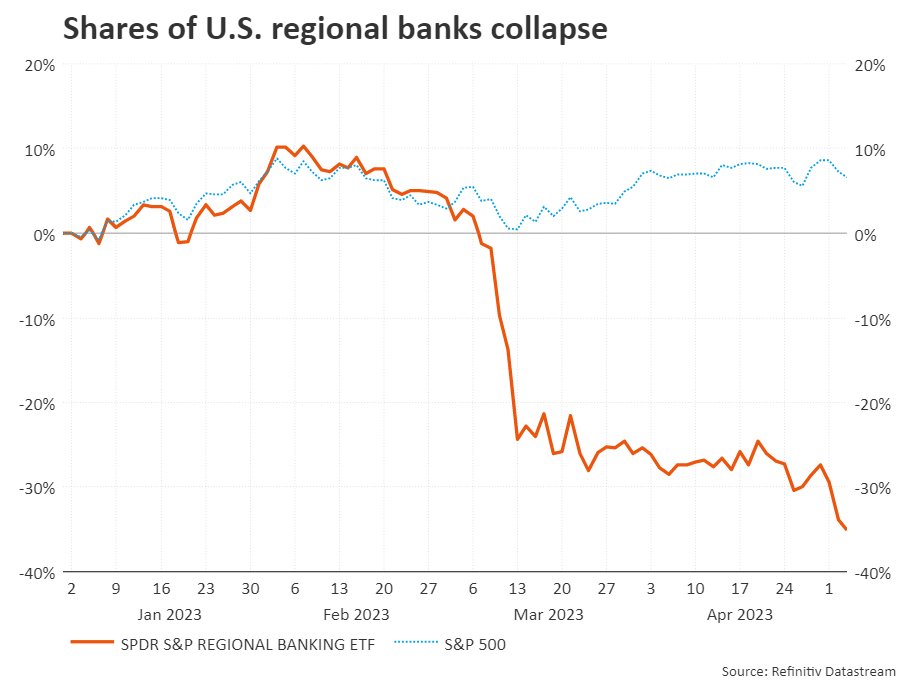
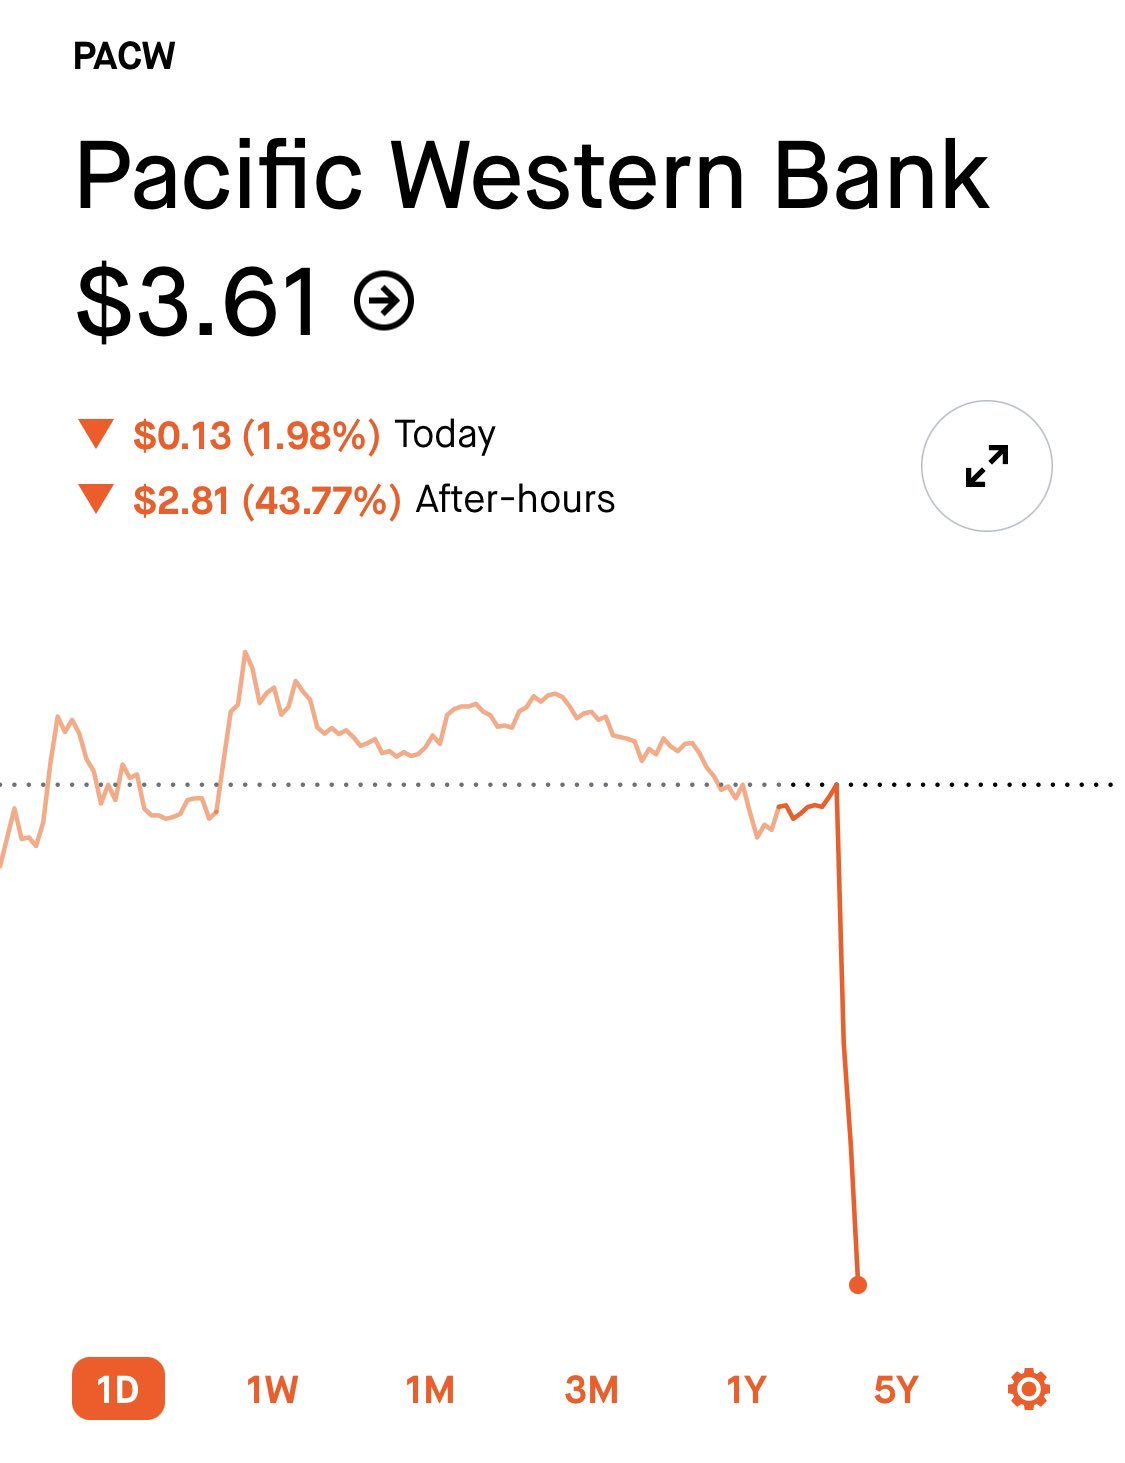
The crisis has sparked renewed calls for the FDIC and Treasury Secretary Janet Yellen to guarantee larger deposits as smaller banks face an uncertain future and customers are anxious about their deposits. A guarantee of deposits above this limit could provide much-needed reassurance to a market in disarray.
However, this issue is polarizing as there are those who argue that guaranteeing deposits above the $250k limit could increase moral hazard, leading to greater risk-taking behavior by banks.
Furthermore, some argue that this is yet another example of the wealthy taking care of their own. According to a survey conducted by the FDIC in 2021, the median bank account balance for households in the US was $3,500. Therefore, if you are securing deposits above $250k, you are essentially securing the funds of the affluent.
Others argue that a guarantee is necessary to prevent further damage to the financial sector and protect customers' deposits.
Bill Ackman has weighed in on the issue, stating that "It is very important for depositors to know that their deposits are guaranteed, particularly during a time of crisis." Ackman believes that deposit insurance is necessary to prevent bank runs and maintain financial stability.
The risks involved if deposits are not guaranteed above the $250k limit could be dire. If customers begin to withdraw their funds from smaller banks, it could trigger a bank run and potentially lead to a wider banking collapse.
The regional banking crisis is a serious issue that has polarized opinions. While some argue that deposit guarantees could increase moral hazard, others believe they are necessary to prevent further damage to the financial sector and protect customers' deposits.
I’m not gonna pretend to have the answer to this dilemma as I see both sides. Trust in the system is key, and maybe increasing the limit could lead to more confidence in the system, therefore less banks failing, and less need for the bailouts in the first place, saving the DFIC money.
But can the DFIC even afford to insure deposits above $250k if the system collapses? Are bailouts really the answer every time the system cracks?
💬 100🔁 287
♥ 909👁 747K